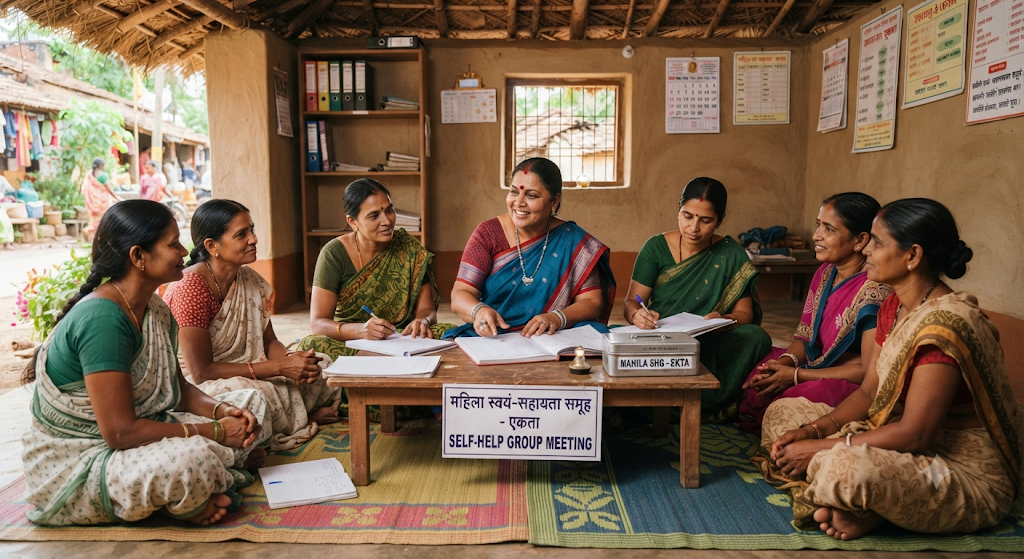
Long before “financial inclusion” became a policy buzzword, women across India were already building it themselves — through Self-Help Groups (SHGs), small collectives that pool savings, offer credit, and give members a level of financial independence many never had access to before.
What a Self-Help Group Actually Is
An SHG is typically a small group of 10-20 women who regularly pool small savings into a shared fund, from which members can borrow for personal or business needs — often without the collateral requirements or paperwork barriers that keep many women out of formal banking systems.
Why Banks Weren’t Working for These Women
Many women, especially in rural areas, historically had no independent credit history, no assets in their own name, and no formal employment record — all things traditional banks require. SHGs sidestepped this entirely by building trust and accountability within the group itself, rather than requiring external collateral.
Beyond Just Savings and Loans
Many SHGs have expanded well past simple savings circles into small collective businesses — food processing units, tailoring cooperatives, handicraft production — giving members not just credit access but an actual income stream, run and controlled by the group itself.
The Confidence Shift
For many women, especially those who had never handled money independently before, participating in an SHG’s financial decisions — voting on loans, managing shared funds, negotiating with buyers — builds a kind of confidence and decision-making experience that extends well beyond the group’s finances.
Government and Institutional Backing
Various national and state-level programs have worked to formalize and scale the SHG model, linking groups to bank credit at better terms and providing training — recognition that this grassroots model, largely built and run by women themselves, was already working better than many top-down alternatives.
The Ripple Effect on Families and Villages
Money earned or saved through SHGs often goes directly toward things like children’s school fees, healthcare, or home improvements — decisions frequently made by the women themselves, in households where financial decisions had previously been made almost entirely by men.
Bottom Line
Self-help groups are one of the clearest examples of a women-led model succeeding not because of external funding alone, but because of trust, accountability, and shared decision-making built entirely within the group. It’s a quiet but genuinely significant force behind rural women’s growing financial independence across India.

